
Last updated September 23, 2026
Free visual inspection and a written scope of work before any mitigation begins - photos, moisture readings, and drying logs go in your claim file
The scope we write is the scope we bill. Anything new gets shown to you, in writing, before we touch it.
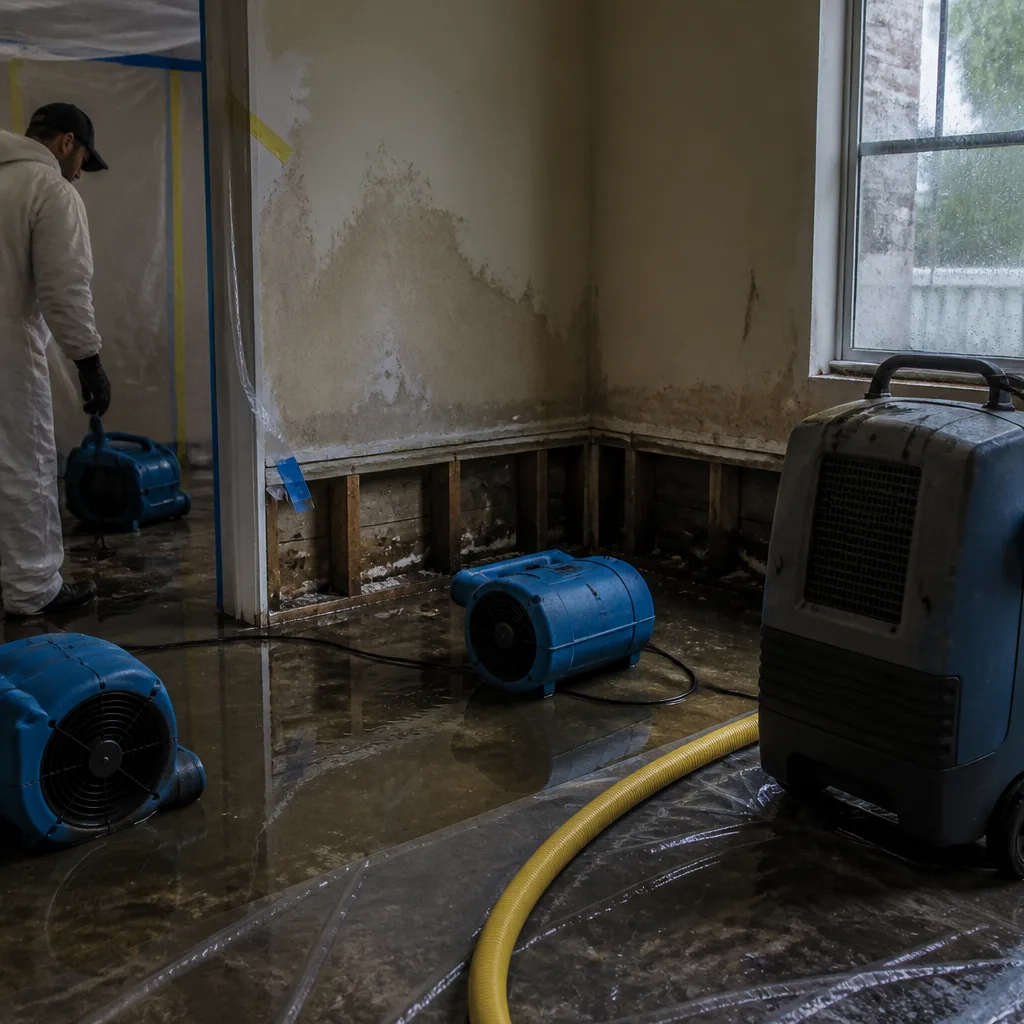 Before
 After
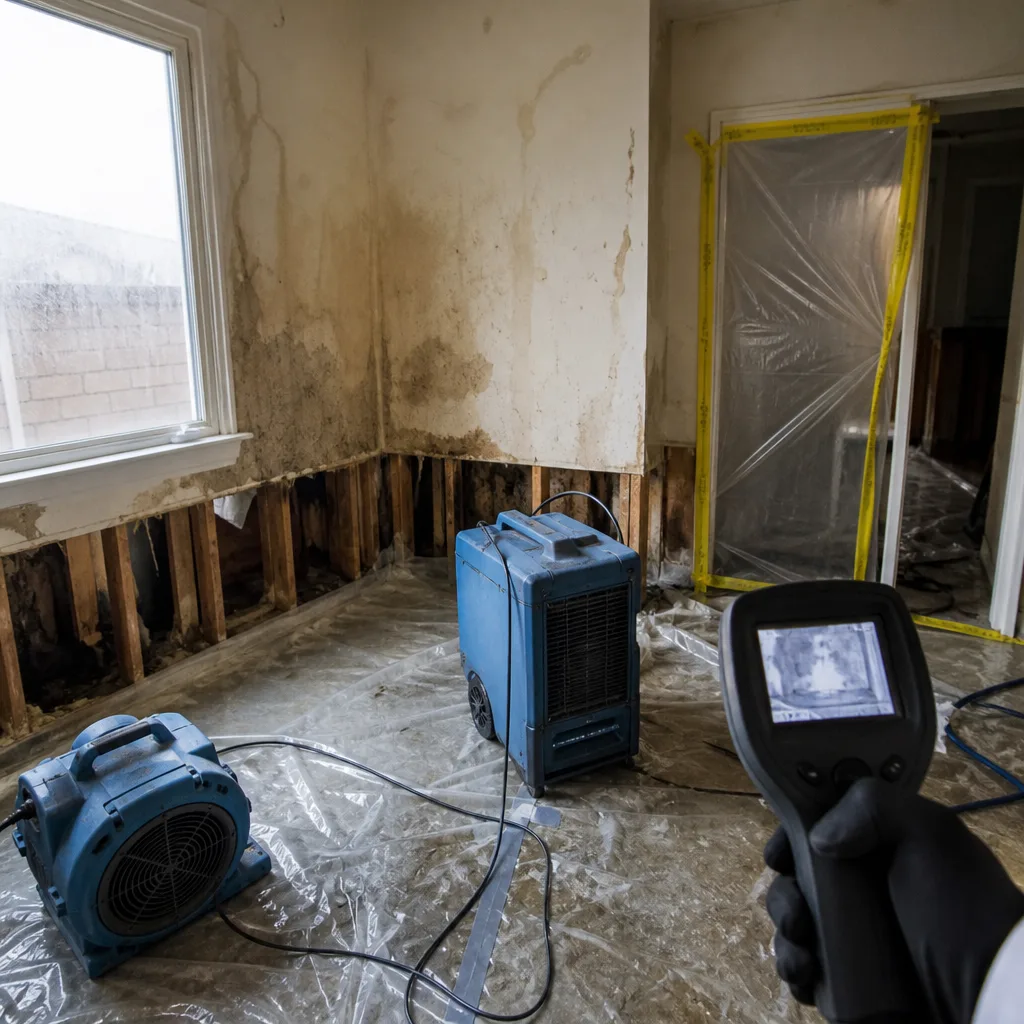 Before
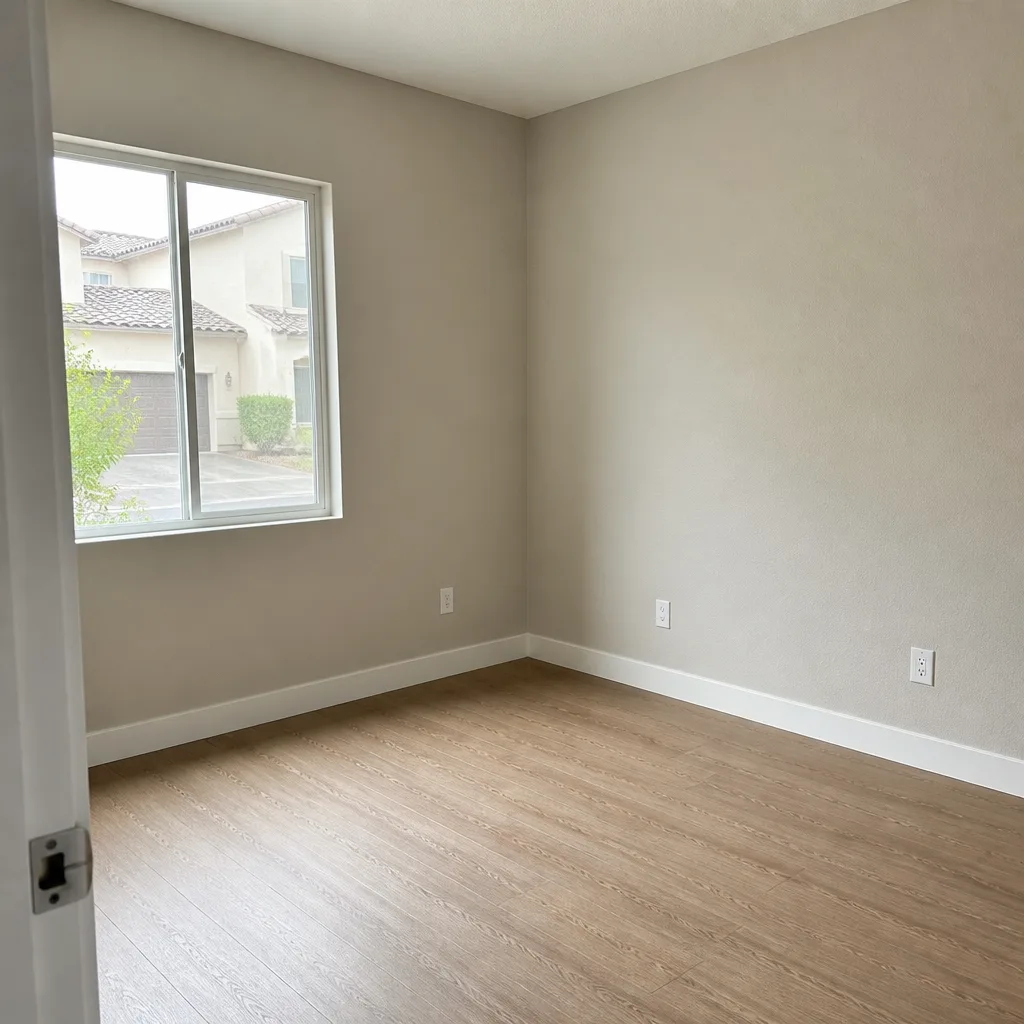 After
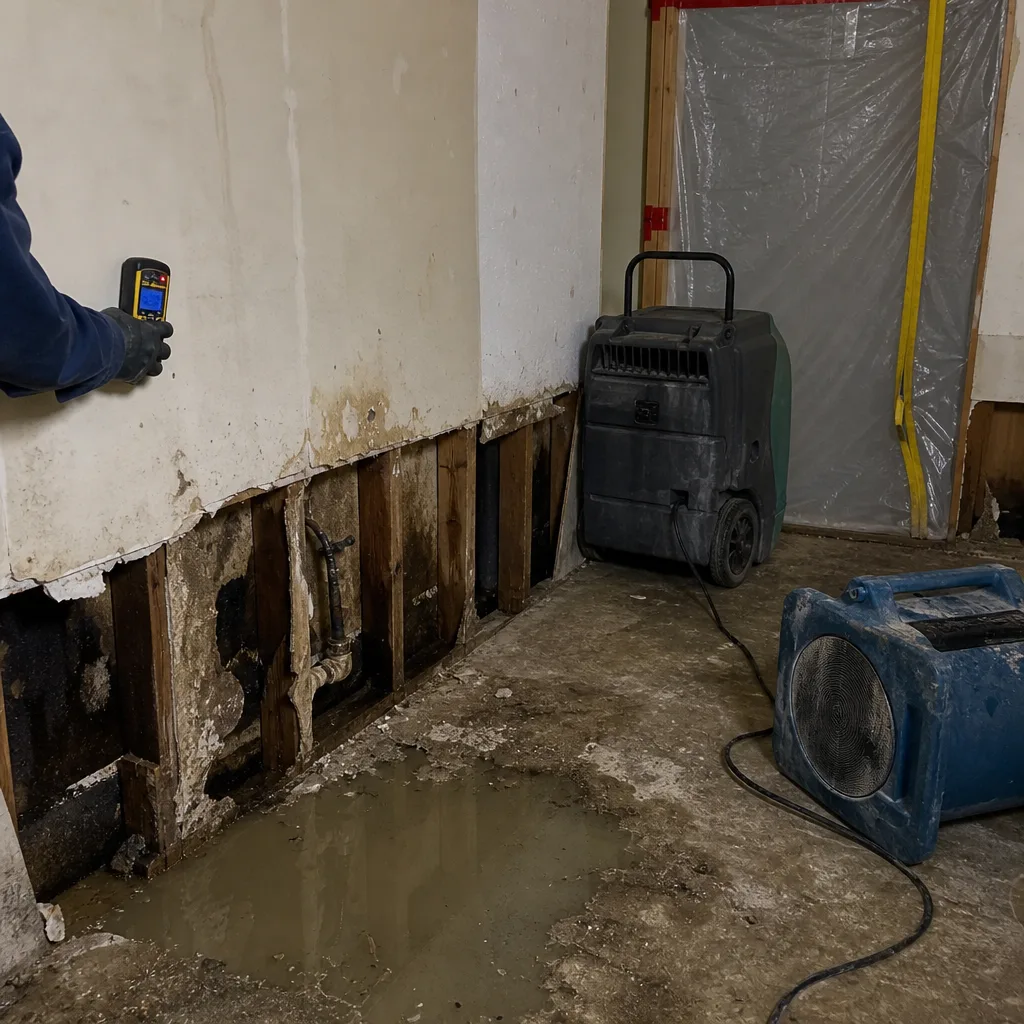 Before
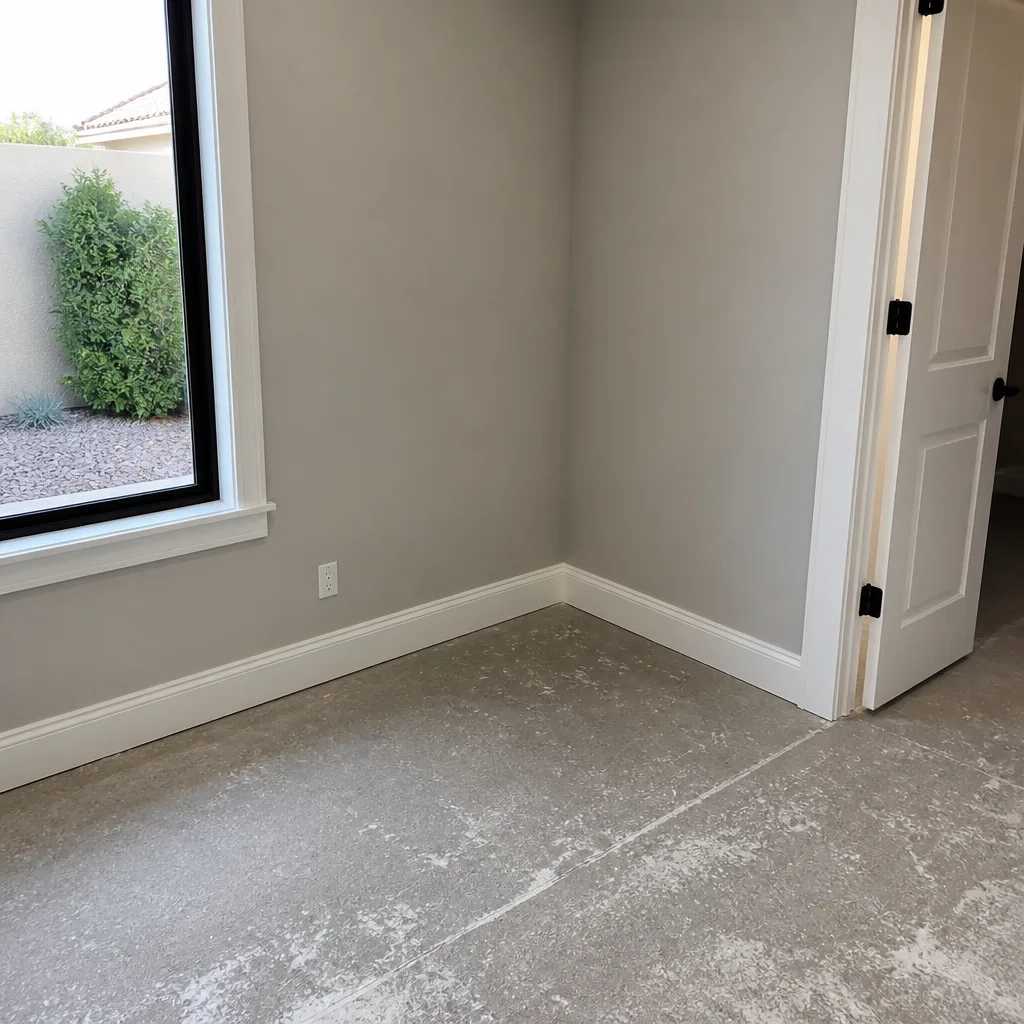 After
The Complete Guide to Damage Restoration in Summerlin
Nevada insurers deny or reduce restoration claims most often not because damage didn’t occur, but because the documentation submitted can’t prove when it started, how far it spread, or what standard of drying was applied. In Summerlin, where caliche soil and hard water create hidden pipe corrosion that can smolder for months before discovery, that documentation gap is especially costly. This guide maps the five phases of every restoration project and the written evidence that should exist at the close of each, so you can turn a crisis into a clean claim file. For damage restoration warning signs every Summerlin homeowner should know, see our companion guide.
Quick Answer
Damage restoration in Summerlin is a five-phase sequence: emergency mitigation, assessment, drying, reconstruction, and final documentation. Each phase produces specific written records, moisture readings, and photo evidence that determine whether your insurer pays the full claim or demands a re-inspection. Proper documentation starts before any equipment runs.
Table of Contents
- The Five Phases of Restoration (And What Paper Each Produces)
- How Summerlin’s Caliche Soil and Hard Water Create Hidden Damage
- Why Your Moisture Baseline Reading Is Your Claim’s Foundation
- Mitigation Invoice vs. Reconstruction Scope: Why They Must Stay Separate
- How to Read Your Certificate of Completion
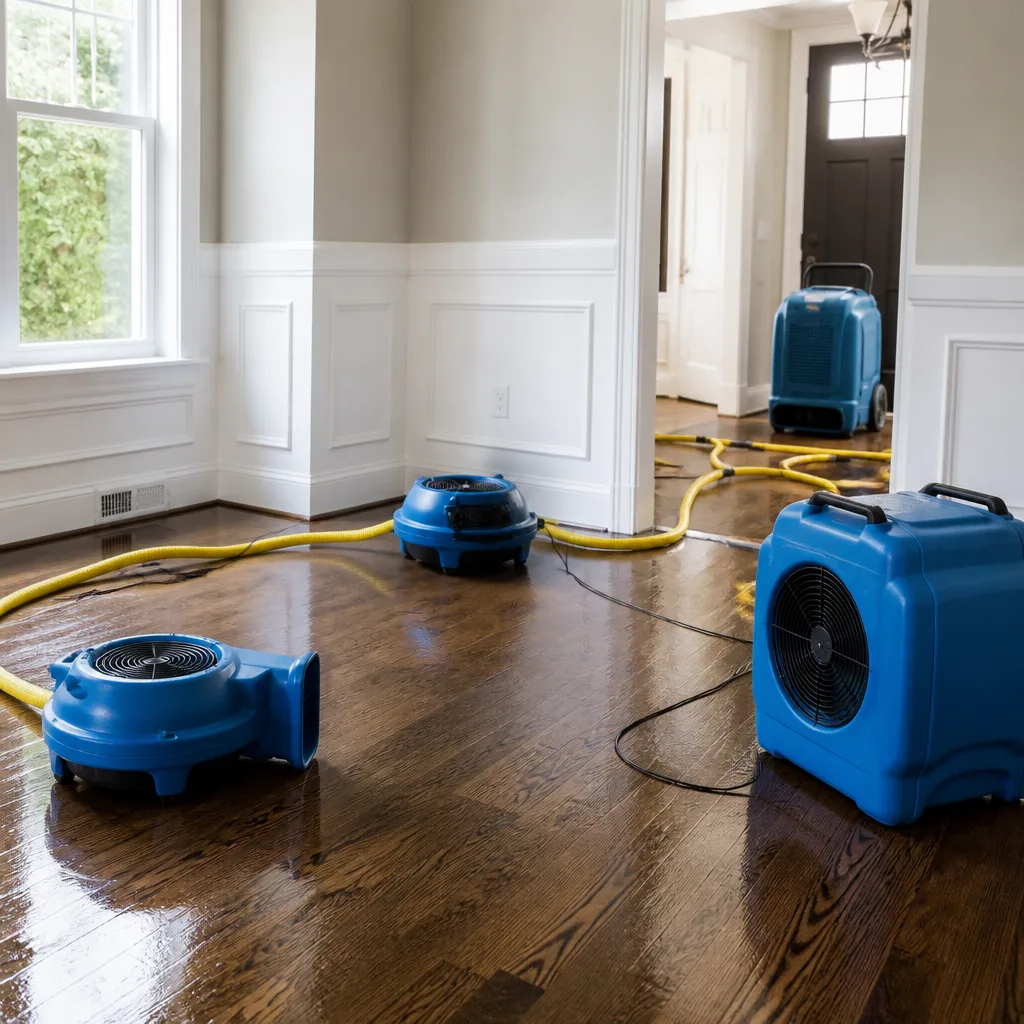
- What Professional Drying Equipment Actually Does
- Common Mistakes to Avoid
- When to Call a Professional
- Frequently Asked Questions
- The Bottom Line
BeforeAfterThe Five Phases of Restoration (And What Paper Each Produces)
Most homeowners in Summerlin think of restoration as the day the trucks arrive. In our experience since 2011, it’s actually a chain of documented decisions, and the weakest link determines your settlement.
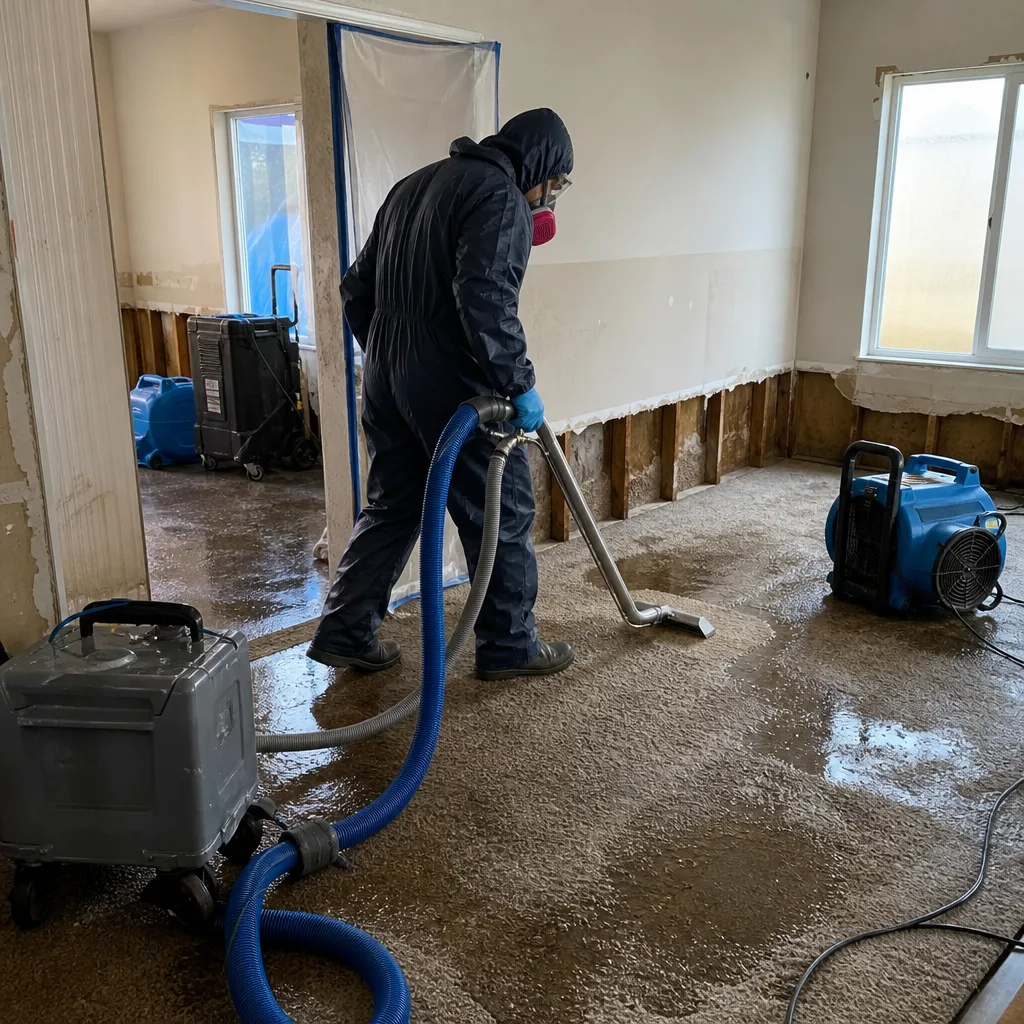
Phase 1: Emergency Mitigation
This is the stop-the-bleeding phase. For water damage, it means extraction, containment, and establishing a dry line. For fire damage, it’s board-up, soot stabilization, and odor control. The written output should be a Mitigation Authorization with a not-to-exceed dollar amount, signed before work begins.
What to demand at this phase:
- A written price before any work starts (Haven Standard, Clause 1)
- Photo documentation of every affected room, timestamped
- Moisture readings for every wet material, recorded on a grid map
- Classification of water category (1, 2, or 3 per IICRC S500)
- Psychrometric conditions: temperature, relative humidity, and dew point
Psychrometric data sounds technical, but it’s simply the atmospheric conditions that determine how fast materials release moisture. Without it, an adjuster can’t verify your drying plan was appropriate for the environment.
Phase 2: Assessment and Scope
Once the emergency is contained, a full assessment determines what must be removed, what can be dried in place, and what reconstruction will cost. This phase produces the Restoration Scope of Work, a room-by-room document with line-item pricing.
In Summerlin’s 89134 and 89144 zip codes, we regularly see homes with engineered wood flooring over concrete slabs. The assessment must specify whether the flooring is salvageable through tertiary drying (targeting the deep substrate after surface drying completes) or must be removed. That single determination can swing a claim by $8,000-$15,000 in this market.
Phase 3: Drying and Stabilization
This is where equipment runs and daily logs matter. A proper drying phase produces:
- Daily moisture logs showing readings for each affected material, compared against the baseline established in Phase 1
- Equipment placement maps showing where each air mover, dehumidifier, or Injectidry system is positioned
- Psychrometric readings taken at the same time each day, documenting vapor pressure differential (the force that actually pulls moisture from materials into the air)
- Progress photos showing visible changes and any materials removed
Vapor pressure differential is the engine of drying. When the air holds less moisture than the wet material, moisture moves out. When that differential stalls, drying stops even if equipment still runs. Daily logs catch that stall and justify equipment adjustments or extensions.
Phase 4: Reconstruction
Reconstruction is scheduled work, not emergency response. The scope is priced in writing, materials are ordered, and permits are pulled where required. In Summerlin, the City of Las Vegas building department requires permits for structural repairs, electrical work, and plumbing modifications. Your contractor should handle permit submission and include the permit number in the final documentation package. See Damage Restoration Permits, Codes & Inspections in NV: What You Need to Know for details.
The reconstruction phase produces:
- A signed reconstruction agreement with milestone payments
- Material specifications by manufacturer and product line
- Permit applications and approvals
- Inspection sign-offs where applicable
- Change orders in writing for any scope modification
Phase 5: Final Documentation
This is the package that goes to your insurer. It should include every document from the previous phases, plus a Certificate of Completion with three critical fields (detailed in a later section). Without complete Phase 5 documentation, even a perfectly executed restoration can face claim reduction.
How Summerlin’s Caliche Soil and Hard Water Create Hidden Damage
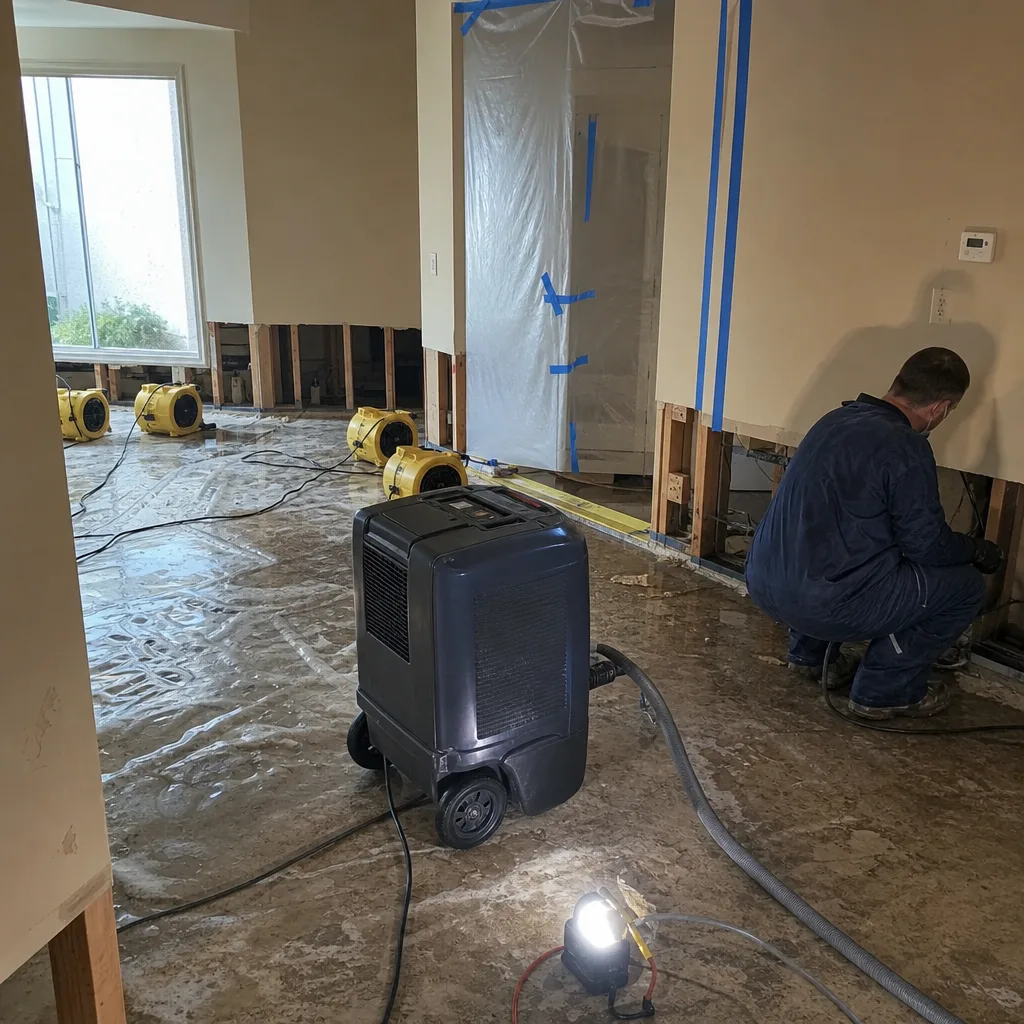
Summerlin sits on the edge of the Mojave Desert, built over caliche: a cement-like layer of calcium carbonate that forms where evaporation exceeds rainfall. Caliche is nearly impermeable. When a pipe leaks beneath a Summerlin slab, water doesn’t drain away. It spreads laterally, sometimes traveling 20 feet or more along the slab edge before showing surface signs.
This matters for your claim because of the discovery date. Nevada insurance policies typically cover sudden and accidental damage, not long-term leaks. A pipe that corroded for eight months before visible staining appears creates coverage disputes. The insurer may argue the damage started before the policy period, or that it resulted from maintenance neglect rather than a covered peril.
Hard water compounds the problem. Summerlin’s municipal water supply averages 280-320 ppm total dissolved solids, with high calcium and magnesium content. Those minerals plate the interior of copper and galvanized pipes, creating localized corrosion cells that pit through the wall. The leak starts pinhole-small, often in a wall cavity or beneath a slab where no one sees it.
What this means practically: when you notice any sign of water damage in Summerlin, photograph it immediately with a timestamp. Note the exact location. Check adjacent rooms, baseboards, and flooring seams. The documentation you create in the first hour often determines whether your claim is accepted as sudden and accidental or disputed as long-term deterioration.
We’ve restored homes in The Trails, The Gardens, and Red Rock Country Club where the visible damage was 15 feet from the actual leak origin. Without thermal imaging and moisture mapping, those homeowners would have filed claims describing damage at the wrong location, with the wrong cause, and with a timeline the insurer could challenge.
Why Your Moisture Baseline Reading Is Your Claim’s Foundation
Every material in your home has a normal moisture content range. In Summerlin’s dry climate, that baseline runs lower than in humid regions, but it still exists and still matters.
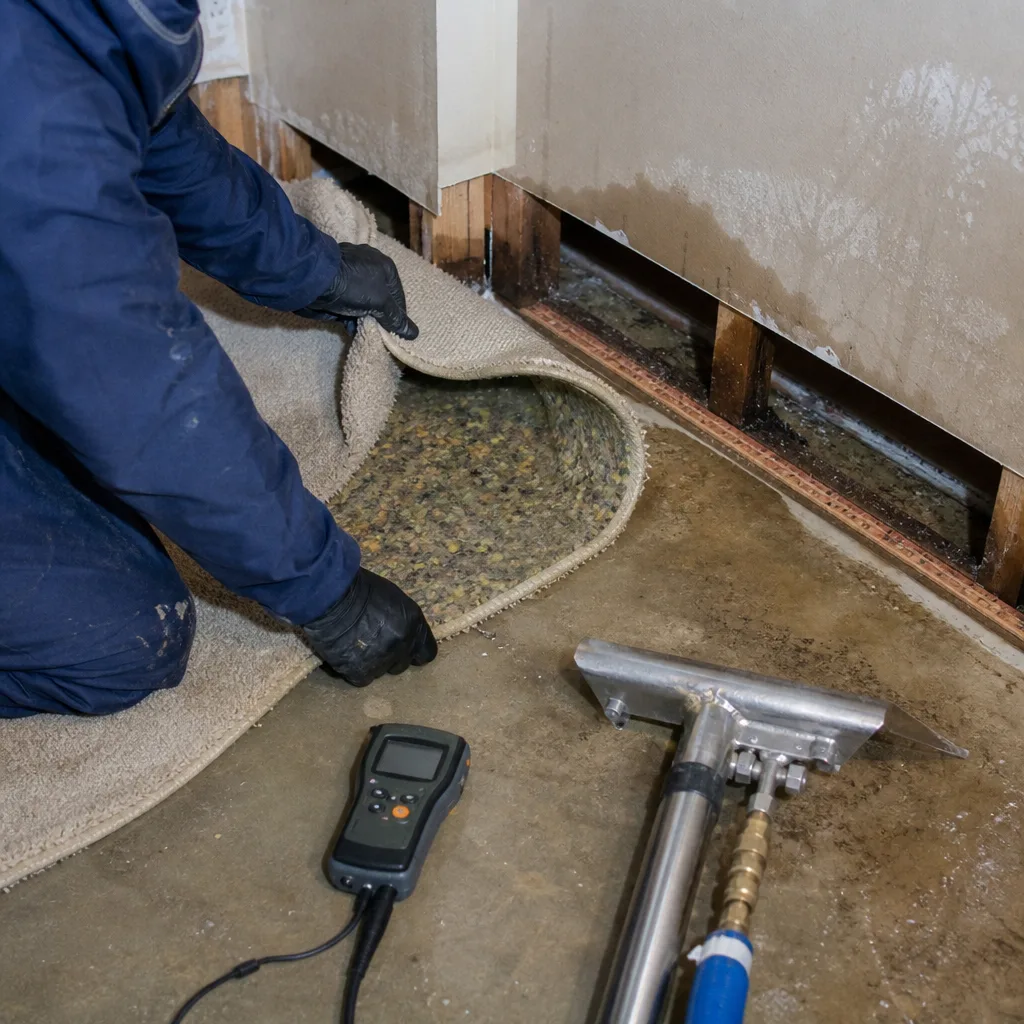
A proper baseline reading is taken with a calibrated pin or pinless moisture meter in an unaffected area of the same material. For drywall in a Summerlin home, that’s typically 5-9% moisture content. For solid oak flooring, 6-10%. For concrete subfloors, readings are taken with a calcium chloride test or relative humidity probe per ASTM F2170.
The baseline serves three functions:
- It proves pre-loss condition. If your insurer later questions whether a floor was already warped, the baseline shows what “normal” looked like.
- It sets the drying target. Drying continues until affected materials return to within 2-3 percentage points of baseline, not until they “look dry” or “feel dry.”
- It justifies equipment duration. Daily logs showing progress toward baseline prove the drying plan was appropriate and equipment was not left running unnecessarily.
A contractor who skips the baseline reading has already undermined your claim. Without it, there’s no objective standard for “done.” The insurer can argue equipment ran too long, or that materials were declared dry prematurely and later failed.
At Water Damage Restoration in Summerlin, we record baseline readings on a grid map of each affected room, with meter calibration dates noted. That map becomes Exhibit A if an adjuster questions our drying protocol.
Mitigation Invoice vs. Reconstruction Scope: Why They Must Stay Separate
This is where many Summerlin homeowners and even some contractors create claim problems that are entirely avoidable.
Mitigation is emergency work: extraction, demolition of unsalvageable materials, drying, sanitizing. It’s billed on a time-and-materials or unit-price basis, often with equipment rental by the day. Mitigation invoices are typically paid quickly by insurers because the work is urgent and the alternative (mold growth, structural rot) is more expensive.
Reconstruction is scheduled build-back: drywall, flooring, paint, cabinetry, fixtures. It’s priced as a construction project, with material costs, labor hours, and overhead markup. Reconstruction scopes are scrutinized more closely because they resemble remodeling, and insurers apply depreciation and comparable pricing.
When these two phases are combined in one document, adjusters notice. It creates several problems:
- The emergency premium built into mitigation rates gets applied to reconstruction work, inflating the total
- Depreciation calculations that apply to reconstruction get incorrectly applied to mitigation
- Line items become unclear: is “remove and replace drywall” one action or two, with what labor allocation?
- The homeowner can’t verify whether mitigation was actually completed before reconstruction began, a sequencing requirement in most policies
Proper documentation keeps these phases financially and temporally distinct. The mitigation invoice closes with a Certificate of Completion showing dry standards met. The reconstruction scope opens with a new agreement, new pricing, and new timeline. At DryMark Restoration Summerlin, we deliver these as separate documents, each with its own photo record, because Haven Standard, Clause 1 applies to every written price, and combining phases would obscure what the price actually covers.
How to Read Your Certificate of Completion
The Certificate of Completion is the document that tells your insurer the job is done and the standards were met. Not all certificates are equal. Here’s what to look for, and what adjusters look for.
Field 1: Moisture Content Verification
The certificate should list final moisture readings for every material that was wet, with the baseline reading noted for comparison. It should specify the meter used and the standard referenced (IICRC S500 for water damage, IICRC S520 for mold). A certificate that says “area dry” without numbers is worthless to an adjuster.
Field 2: Equipment Removal Date and Total Runtime
This field documents when drying equipment was removed and how many days it ran. It should match the daily logs. Discrepancies here trigger re-inspection. In Summerlin’s low-humidity climate, drying typically completes faster than in coastal regions, but “faster” still means documented achievement of dry standards, not arbitrary removal.
Field 3: Post-Remediation Verification (PRV) for Mold or Category 3 Water
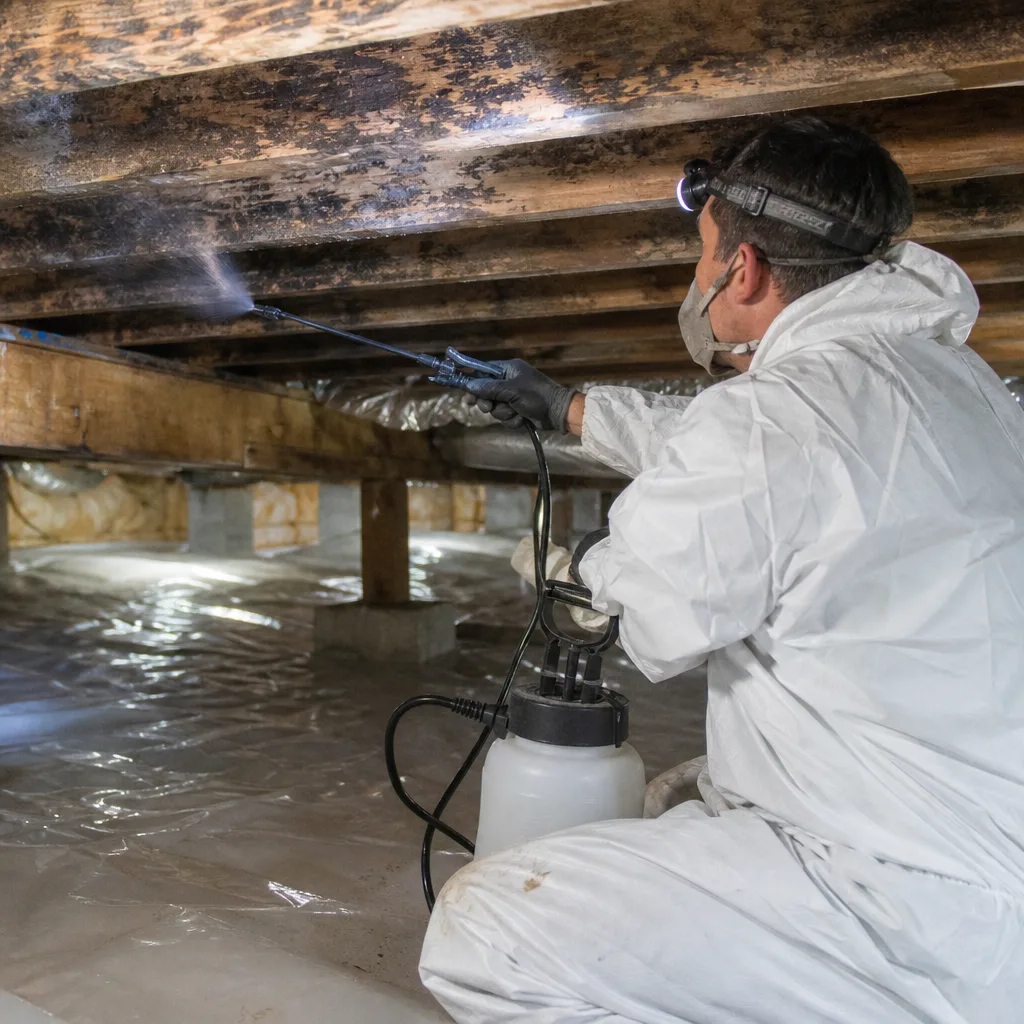
If mold was present or water was Category 3 (sewage or ground water), the certificate should include PRV results: air sampling or surface sampling showing clearance levels met. The lab name, sample date, and analytical method should be specified. A contractor’s visual “looks clean” assessment is not PRV.
We’ve reviewed competitor certificates where all three fields were blank or generic. Those homeowners faced re-inspections, delayed settlements, and in two cases we handled, claim denials that a proper certificate would have prevented. Our Mold Remediation in Summerlin includes third-party PRV as standard, with lab documentation delivered with the certificate.
What Professional Drying Equipment Actually Does
Equipment names on an invoice should correspond to specific functions, and those functions should match your damage type. Here’s what the major systems do, in plain terms.
Low-grain refrigerant (LGR) dehumidifiers (brands like Dri-Eaz and Phoenix) remove water vapor from air by cooling it below the dew point, then reheating it before discharge. “Low-grain” means they work efficiently even when the air is already fairly dry, which matters in Summerlin’s climate where ambient humidity runs 15-25% much of the year. Without LGR technology, a dehumidifier would stop extracting moisture just when you need it most.
Air movers (brands like XPOWER and B-Air) don’t dry materials directly. They accelerate evaporation by disrupting the boundary layer of saturated air that clings to wet surfaces. Placement matters: one air mover per 50-70 square feet of affected floor, positioned to create a vortex pattern that drives moisture toward the dehumidifier intake.
Injectidry systems address trapped moisture in wall cavities, cabinet toe-kicks, and beneath hardwood flooring. They use negative air pressure to pull dry air through confined spaces, or positive pressure to force it in. In Summerlin homes with blown-in insulation or spray foam, Injectidry is often the only way to dry structural cavities without full demolition.
Desiccant dehumidifiers use silica gel or lithium chloride to absorb moisture chemically, rather than by condensation. They’re essential for deep drying in cold environments or where very low humidity targets are required, but in Summerlin’s warm climate, LGR units are typically more energy-efficient for residential work.
The equipment deployed on your job should be listed on the daily log with serial numbers or asset tags, run hours, and placement locations. This isn’t bureaucracy. It’s how you prove to an insurer that the drying plan was appropriate and executed as specified.
Our equipment is documented to IICRC, RIA, and IFA standards, with daily logs produced on every job. When we deploy a Phoenix 200 MAX or Dri-Eaz Evolution in a Summerlin home, the model, serial, and runtime appear in your file, along with the psychrometric conditions that justified its selection.
Common Mistakes to Avoid
- Waiting to document until the contractor arrives. In Summerlin’s hard-water environment, mineral staining begins within hours and can be mistaken for long-term damage. Photograph everything before anyone touches it.
- Accepting a verbal estimate or “ballpark” figure. Haven Standard, Clause 1 exists because verbal pricing creates disputes. If a contractor won’t put a price in writing before starting, that’s not flexibility, it’s a red flag.
- Allowing mitigation and reconstruction to be billed as one phase. This invites depreciation errors, rate confusion, and adjuster re-inspection. Each phase deserves its own written scope.
- Not requesting the drying logs. Some contractors treat logs as internal documents. They’re not. They’re your evidence that drying standards were met, and you’re entitled to them.
- Ignoring permit requirements for reconstruction. The City of Las Vegas requires permits for structural, electrical, and plumbing work. Unpermitted reconstruction can void your insurance coverage and create title problems when you sell.
- Signing a certificate of completion you don’t understand. If moisture readings, equipment dates, or PRV results are missing or unclear, ask for clarification before signing. Your signature certifies acceptance.
- Discarding documentation after payment. Keep all records for at least five years. Secondary damage claims, latent defects, and insurer audits can arise long after the work is done.
When to Call a Professional
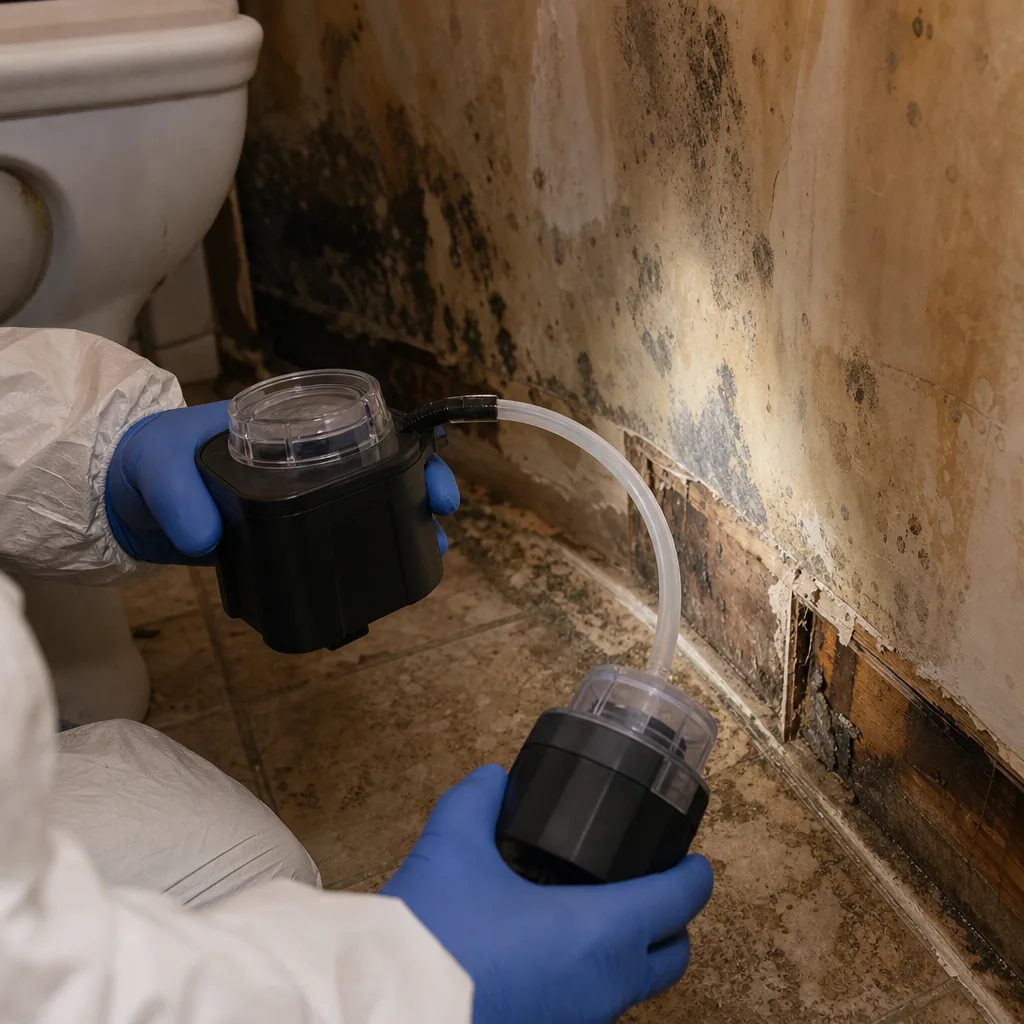
Call immediately when water is actively flowing, when you smell mold or see it covering more than 10 square feet, when sewage is involved, or when fire damage has compromised structural elements or electrical systems. These situations worsen by the hour and create health risks that DIY efforts can’t address safely.
Call within 24 hours when you discover staining, warping, or odor that suggests hidden moisture, even if the source seems minor. In Summerlin’s caliche soil conditions, a small surface sign often masks extensive lateral spread beneath slabs or behind walls.
DryMark Restoration Summerlin offers free estimates in Summerlin, with a written price delivered before any work begins and a documented photo record on every visit. For emergency response or a free second opinion on any competitor’s written estimate, call (725) 216-2692. Live phone coverage is available 24 hours a day, 7 days a week with no voicemail on emergency lines.
Frequently Asked Questions
Water damage mitigation in Summerlin typically ranges from $1,200 for contained clean-water extraction to $6,500+ for whole-house drying with category 3 contamination. Reconstruction is priced separately, with drywall replacement at $2.50-$4.00 per square foot and engineered wood flooring at $8-$14 per square foot installed in this market. For a full breakdown, see our Damage Restoration Cost Breakdown: The Summerlin Homeowner’s Reference for 2026. Every job receives a written price before work starts, with no scope-creep additions once the crew is inside. Call (725) 216-2692 for an exact quote, estimates are free.
Your insurer will cover what your policy language and documentation support. The most common reason for partial denial is inadequate documentation of the damage origin, extent, and drying standard applied. A properly documented job, with baseline moisture readings, daily logs, and a complete Certificate of Completion, is paid without dispute in our experience. We coordinate directly with adjusters and provide photo-documented evidence packages as standard. Browse our more guides & resources for additional homeowner references. Call (725) 216-2692 to discuss your specific policy situation.
For active water flow, sewage backup, or fire damage with structural compromise, emergency crews are dispatched immediately, live person answers every call 24 hours a day, 7 days a week. Drying and stabilization equipment is typically placed within 2-4 hours of authorization. Reconstruction is scheduled, not emergency-dispatched, and is scoped in writing with a timeline before work begins. Call (725) 216-2692 for current emergency response availability.
For water damage under 10 square feet from a clean source, with no porous materials affected, DIY extraction and drying may suffice. For anything larger, anything involving drywall or insulation, any category 2 or 3 water, or any mold growth, professional remediation is necessary for health reasons and for documentation that protects your insurance claim. In Summerlin’s climate, mold can colonize within 48-72 hours of water intrusion. Our DryMark Restoration Summerlin home page lists the specific services and documentation standards we apply.
We do, as part of our standard service. Our documentation packages, including daily drying logs, photo records, and written scopes, are formatted for direct adjuster submission. We participate in adjuster site visits when requested and provide supplemental documentation if questions arise. This coordination is included, never an upsell. Haven Standard, Clause 1 applies to every interaction: nothing is promised verbally that isn’t confirmed in writing.
Most warranties cover defects in materials or workmanship that you discover and report. Our 365-Day Done Right Promise, backed by The Haven Standard, means that if any aspect of our work fails to meet the documented standard within one year, we return and correct it at no charge, even if the issue wasn’t initially apparent. It’s a signed guarantee, not a verbal assurance, and it’s stamped on every job file. We’ve honored this promise 47 times since 2011, always with the same documentation rigor we apply to the original work.
The Bottom Line
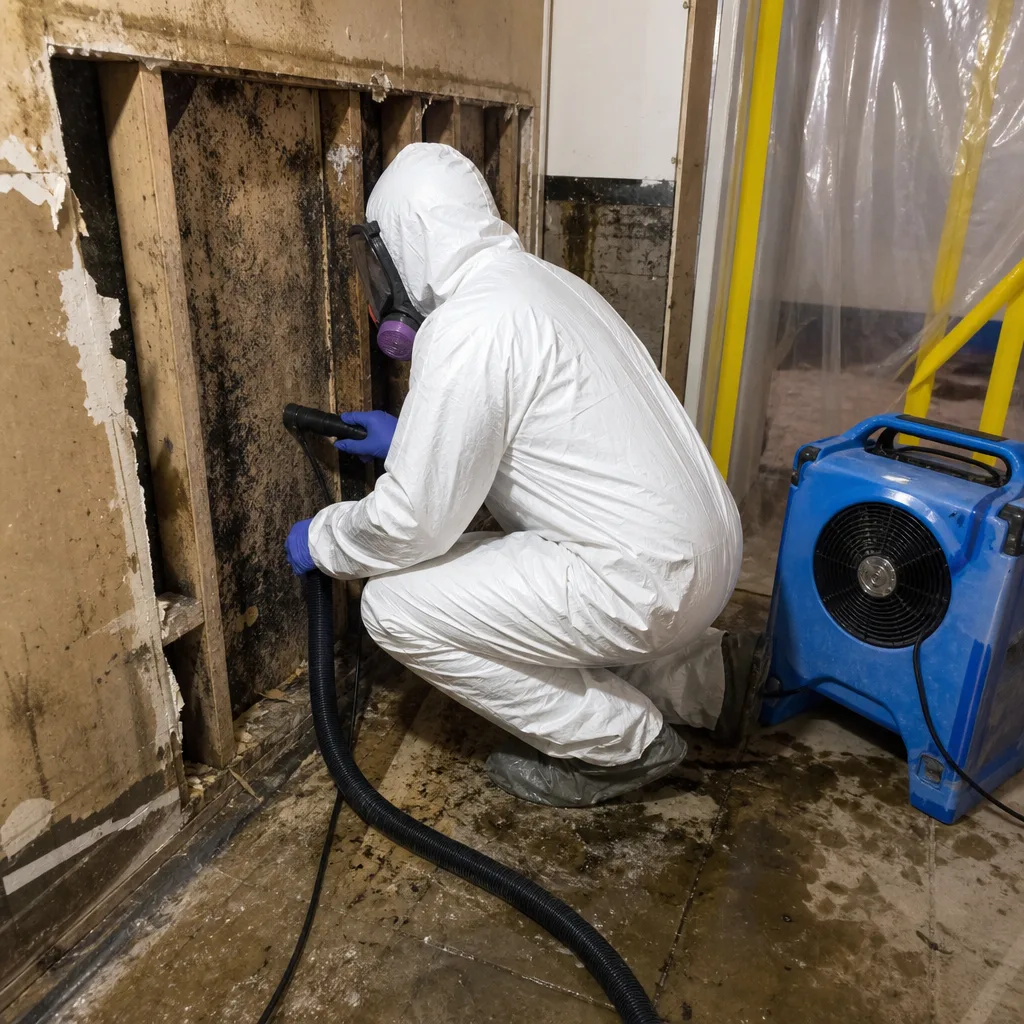
Damage restoration in Summerlin is not a single event to survive. It’s a sequence of five documented phases, each producing written evidence that either strengthens or weakens your insurance claim. The homeowners who recover fully are those who treat documentation as seriously as drying: baseline readings established before work begins, daily logs maintained throughout, phases kept financially distinct, and a Certificate of Completion that an adjuster can verify without re-inspection.
Summerlin’s caliche soil and hard water create unique hidden damage risks that make the discovery date and moisture mapping especially critical. The contractor you choose should understand these local conditions and build documentation around them, not despite them.
At DryMark Restoration Summerlin, every job since 2011 has operated under The Haven Standard: written price before work begins, photo record on every visit, and the 365-Day Done Right Promise backed by a signed guarantee. For a free estimate or a free second opinion on any competitor’s written estimate, call (725) 216-2692.
Written by Alicia Brennan, Owner at DryMark Restoration Summerlin, serving Summerlin since 2011.